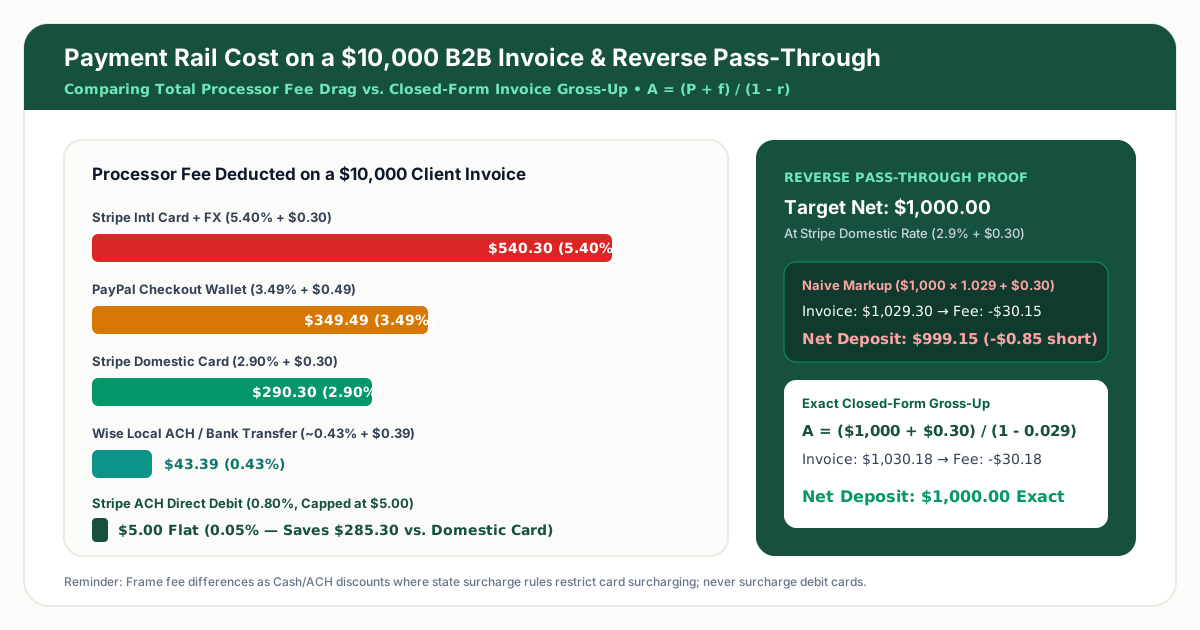
The $625 Math Inflection Point: Why Cards Bleed High-Ticket Freelancers
Credit card merchant networks price transactions proportionally—2.90% + $0.30 on Stripe or 2.99%–3.49% + $0.49 on PayPal—because card networks underwrite instant authorization, airline rewards, and consumer chargeback insurance. While 3% feels tolerable on a $50 SaaS subscription ($1.75), it becomes punitive on $5,000 to $25,000 B2B consulting retainers.
In contrast, Stripe ACH Direct Debit charges 0.80% capped strictly at $5.00 per settled transaction. That mathematical ceiling kicks in at exactly $625.00 ($625 x 0.008 = $5.00). Above $625, your effective merchant fee percentage actually falls as your invoice grows—dropping to 0.10% on a $5,000 project and 0.02% on a $25,000 milestone.
| Invoice Size | PayPal Checkout (3.49%+$0.49) | Stripe Card (2.9%+$0.30) | Wise Local ACH (0.43%+$0.39) | Stripe ACH (0.8%, $5 Cap) |
|---|---|---|---|---|
| $500 | $17.94 (3.59%) | $14.80 (2.96%) | $2.54 (0.51%) | $4.00 (0.80%) |
| $2,000 | $70.29 (3.51%) | $58.30 (2.92%) | $8.99 (0.45%) | $5.00 (0.25%) |
| $5,000 | $174.99 (3.50%) | $145.30 (2.91%) | $21.89 (0.44%) | $5.00 (0.10%) |
| $10,000 | $349.49 (3.49%) | $290.30 (2.90%) | $43.39 (0.43%) | $5.00 (0.05%) |
| $25,000 | $872.99 (3.49%) | $725.30 (2.90%) | $107.89 (0.43%) | $5.00 (0.02%) |
Eliminating ACH Friction: Instant Bank Verification & Default Rail UX
Historically, freelancers avoided ACH because clients hated waiting 2 days to confirm two random micro-deposits (e.g., $0.14 and $0.27) before an invoice could settle. Modern open-banking rails solve this friction entirely: Stripe Financial Connections (and Plaid-enabled accounting suites like QuickBooks, FreshBooks, or Mercury Invoicing) verify corporate checking credentials in under 15 seconds via OAuth login.
Equally important is payment UX architecture. When clients see 'Pay by Credit Card' pre-selected as the giant primary button and 'ACH' buried in fine print, finance clerks default to corporate cards for points. Reverse the visual hierarchy: enable ACH Direct Debit and bank wire as your primary pre-selected payment tabs, and only expose credit card checkout when paired with a contractually disclosed 3.0% card convenience adjustment or a 2% ACH/Wire early-settlement discount. Need to compute exact card pass-through totals when a client insists on cards? Use our Stripe & PayPal Fee Optimizer.
- Instant OAuth verification (Financial Connections) removes the 48-hour micro-deposit barrier.
- Domestic incoming ACH transfers to business banks like Mercury, Relay, or Chase typically carry $0 incoming bank wire fees (unlike $15–$25 Fedwire fees).
- Use Wise Business exclusively for cross-border USD/EUR/GBP conversions, where Stripe's 4.4%–5.4% international card rates otherwise destroy margins.
Managing ACH Settlement Lag & NACHA Return Risk
ACH is not irrevocable like a Fedwire. Standard ACH debits require 3 to 5 business days to clear, and commercial buyers have up to 60 days (or 2 business days for B2B corporate unauthorized returns depending on SEC codes) to dispute unauthorized debits under NACHA rules. Stripe charges a $4.00 ACH failure fee on NSF returns (R01) or disputes.
Protect cash flow on large milestones by setting invoice due dates 5 business days ahead of payroll or rent obligations, embedding explicit ACH debit authorization language inside your Master Services Agreement (MSA), and requesting direct client-initiated ACH push / wire payments for one-off projects exceeding $25,000.
Client-Initiated ACH Push vs. ACH Debit Pull & Large Wire Thresholds
When invoicing enterprise finance departments, distinguish between ACH Debit Pull (where Stripe pulls funds from the client's bank via Financial Connections for 0.8% capped at $5.00) and Client-Initiated ACH Credit Push (where the enterprise's AP system sends an ACH transfer directly to your business checking routing/account number).
Most modern business checking platforms—including Mercury, Relay, Brex, and major commercial banks—accept incoming domestic ACH credits at $0.00 fee, reducing a $25,000 retainer cost from $5.00 to literally zero. Reserve domestic Fedwire transfers ($15–$25 sender fee, often $0–$15 incoming fee) strictly for time-critical final milestone settlements or property/escrow closings exceeding $50,000 where same-day irrevocable finality justifies the wire fee. Always include both ACH instructions and an invoice-link option with a clearly stated card convenience/discount policy so clients pay on their preferred corporate rail without eroding your margin.
Samir: Fractional CTO & Systems Architect
Samir invoices $180,000 per year across 24 B2B retainers averaging $7,500.00 each from U.S. venture-backed startups. Historically, clients clicked the default credit card button on Stripe or PayPal invoices.
Highest standard B2B domestic fee drag (3.50% effective rate)
Standard card acceptance cost on $7,500 invoices (2.90% effective rate)
Uncapped percentage beats cards, though Wise shines primarily on FX conversions
Hard $5.00 fee cap kicks in at $625; just 0.067% effective fee on $7,500
97.7% reduction in payment processing overhead
Funds nearly an entire year of Solo 401(k) Roth growth or Q4 tax reserve
Stripe & PayPal Fee Optimizer
Model exact card, PayPal, and Wise bank-transfer fees on your typical project invoice size and calculate exact reverse gross-up amounts.